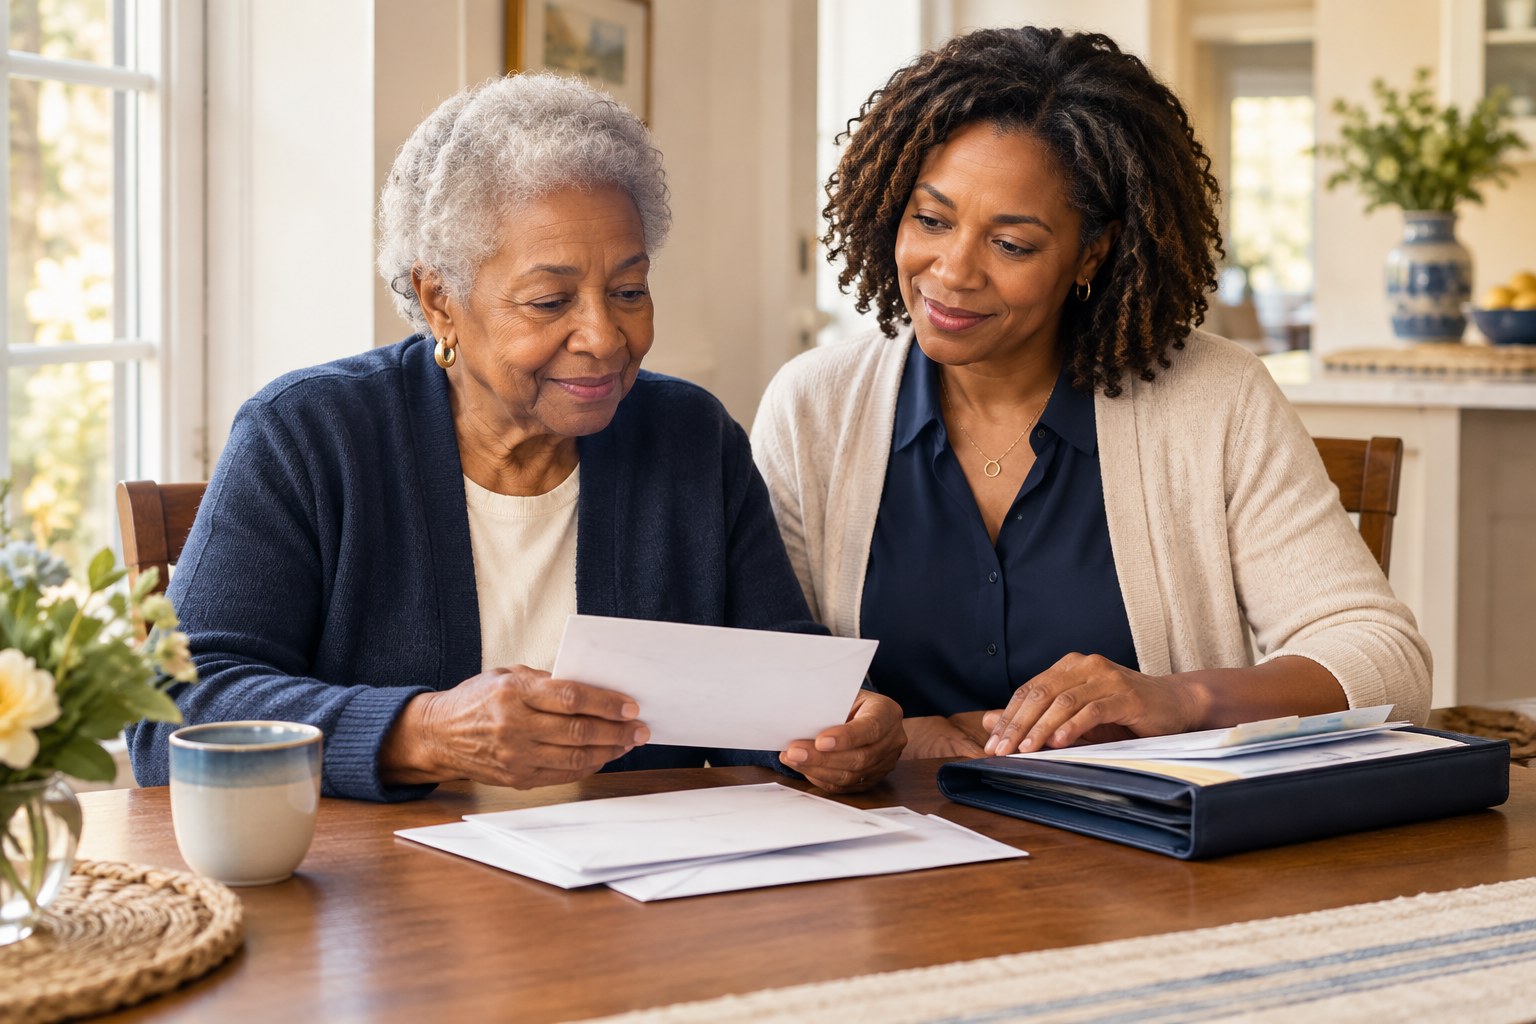

There are moments in watching your parents age when an ordinary object suddenly carries extraordinary meaning. An unopened envelope. A past-due notice. A utility bill tucked beneath a stack of magazines.
You may have visited your parent countless times without paying much attention to the mail. But now something feels different. Your mother, who once balanced her checkbook to the penny, cannot remember whether she paid the electric bill. Your father, who always took pride in managing household finances, seems unusually confused about a bank statement.
What should you do? Your first instinct may be to take over. After all, unpaid bills can threaten utilities, housing, insurance coverage, and financial security. But your parent may need assistance without needing to surrender control. The artistry of watching parents age involves learning to recognize that distinction.
One Missed Bill Is Not a Diagnosis
Forgetting to pay a bill occasionally does not necessarily indicate dementia. The National Institute on Aging explains that occasional forgetfulness can occur with normal aging, while more significant memory problems may interfere with everyday activities. Financial management deserves particular attention because it involves memory, judgment, planning, organization, and decision-making.
Research summarized by the National Institute on Aging has found that financial difficulties sometimes appeared years before a dementia diagnosis, including patterns of missed payments and declining credit performance. These observational findings do not mean every missed payment predicts dementia. They suggest that changes in financial behavior can sometimes offer an opportunity to recognize a problem.
The distinction matters. You are not looking for evidence to prove that your parent is losing independence. You are trying to understand whether a familiar ability has changed. That requires observation rather than accusation.
Notice the Change, Not Merely the Mistake
Suppose your mother has always paid her bills promptly. Over several months, however, you begin noticing unopened envelopes and occasional late-payment notices. The important question is not simply whether a bill went unpaid. It is whether this represents a departure from her established routine.
Has she always disliked paperwork? Did she recently change banks? Is she struggling with an unfamiliar online payment system? Has she experienced illness, bereavement, financial stress, or a medication change? Context transforms an isolated observation into useful information.
The ANCHOR™ approach begins by acknowledging what you are seeing without rushing toward a conclusion. Instead of saying, “Mom, you cannot manage your money anymore,” you might say, “I noticed a couple of bills that appear to be overdue. That’s unusual for you. Has something changed with the way you’re handling them?”
This conversation offers your parent an opportunity to explain what is happening. It also communicates something important: you are approaching the situation as a partner rather than an investigator.
Preserve Dignity Through Permission
Financial independence is closely connected to personal identity. For many older adults, paying bills represents far more than completing an administrative task. It symbolizes competence, responsibility, and the ability to direct one’s own life.
Imagine how unsettling it might feel to discover that your adult child has begun questioning your financial judgment. Even when concerns are legitimate, the manner in which you approach them can determine whether your parent welcomes assistance or withdraws from the conversation.
Begin with permission. Ask whether you may review the concerning bills together. Listen before suggesting solutions. Avoid examining private accounts or financial records without appropriate consent or legal authority. You may discover that your parent understands the problem but needs help organizing paperwork. Perhaps a new payment system is confusing. Perhaps an automatic withdrawal failed.
The Consumer Financial Protection Bureau describes ways families can assist with bill paying while preserving an older person’s control, including informal assistance, trusted contacts, and appropriately established financial powers of attorney. Assistance should be proportionate to the need.
Look for Patterns Across Everyday Life
Financial concerns rarely exist in isolation. As you spend time with your parent, pay attention to other changes that may help explain what is happening. Is your father having difficulty following familiar instructions? Has your mother begun repeating questions about appointments? Are household responsibilities becoming harder to organize?
Equally important, notice what remains unchanged. Your parent may still prepare meals, manage medications, maintain friendships, and make thoughtful decisions about personal matters. Recognizing preserved abilities helps prevent an unnecessarily sweeping judgment about independence.
The goal is not to compile a list of deficiencies. It is to develop an accurate picture of your parent’s current functioning. Document observations factually. “Two utility bills were overdue during September” is more useful than “Dad is becoming incompetent.” Avoid putting account numbers, passwords, or other sensitive financial information into general caregiver notes.
Consider Explanations Beyond Dementia
Changes in memory or financial performance deserve attention, but they should not automatically be attributed to Alzheimer’s disease. The National Institute on Aging identifies several conditions that may affect memory and thinking, including depression, anxiety, sleep problems, medication side effects, thyroid disorders, and nutritional deficiencies. Some contributing conditions may improve with appropriate treatment.
Your parent’s primary care clinician can help evaluate concerning changes. When requesting an appointment, explain the specific functional problem rather than suggesting a diagnosis. You might report that your parent has missed several payments despite previously managing finances independently, or that difficulty understanding familiar statements has become more frequent.
This information can help the clinician determine whether additional evaluation is appropriate. A sudden change in confusion or mental functioning is different from a gradually developing concern. New, acute confusion requires prompt medical assessment rather than waiting to collect more observations. Describe what you see. Do not diagnose what it means.
Protect Essential Needs Without Taking Over Everything
When a financial concern becomes clear, your next responsibility is to help prevent avoidable harm. Start with immediate essentials. Are housing payments current? Are utilities at risk of disconnection? Is health insurance coverage threatened? Have important medications or necessities become unaffordable?
With your parent’s permission, consider practical safeguards such as payment reminders, an organized bill calendar, or automatic payments for predictable expenses. You may also explore whether the financial institution offers a trusted-contact arrangement.
A trusted contact generally provides someone the institution may notify under specified circumstances. It does not automatically authorize that person to withdraw funds or conduct transactions. A durable financial power of attorney is different. It can grant substantial authority, depending on its terms and applicable law. Families should obtain qualified legal guidance before establishing or relying upon such arrangements.
The objective is to provide the least intrusive assistance that adequately addresses the risk. A parent who needs help remembering due dates may not need someone else controlling every financial decision.
Know When the Concern Becomes Urgent
Some financial changes require more immediate intervention. Unexpected withdrawals, unexplained account activity, unfamiliar people exerting influence, or sudden changes in financial arrangements may indicate exploitation. The Consumer Financial Protection Bureau identifies these circumstances among potential warning signs of elder financial abuse.
If exploitation is suspected, contact the financial institution promptly and consider reporting concerns to the appropriate Adult Protective Services agency or law enforcement. For an immediate threat to safety, seek emergency assistance. Financial exploitation and cognitive impairment are not interchangeable. An older adult can be exploited without having dementia, and someone experiencing cognitive changes is not necessarily being exploited. Each concern deserves its own careful assessment.
From Observation to the Next Wise Move
Watching parents age often places you between two competing responsibilities: respecting their independence and protecting their well-being. You do not have to resolve that tension in a single conversation.
Begin with what you know. Acknowledge the concern. Notice whether a pattern is developing. Clarify what may be contributing to the difficulty. Help with immediate needs. Offer proportionate assistance. Route the concern to appropriate professionals when necessary.
These movements reflect the ANCHOR™ philosophy of thoughtful, person-centered caregiving. You are not required to become your parent’s physician, attorney, or financial adviser. You are being invited to become a more attentive observer, a more effective communicator, and a more thoughtful advocate.
The unopened envelope may be a minor oversight. It may signal a need for practical support. Occasionally, it may reveal a more serious problem. Your responsibility is not to know the answer before asking the question. It is to recognize when a question deserves attention.
Your Next Wise Move
If you have begun noticing changes in your parent’s everyday routines, start documenting what you observe. The free ANCHOR™ Pattern Tracking Suite provides practical tools for recording changes over time and preparing for more productive conversations. Explore the Artistry of Eldercare™ Resource Hub.
Closing Reflection
You may not be able to prevent every difficulty your parent encounters. You can, however, approach uncertainty with patience, compassion, and a willingness to understand. Sometimes the most meaningful assistance begins not with taking something away, but with asking how you can help.
Further Reading
For background and practical guidance, consult the National Institute on Aging’s memory and aging resources and the Consumer Financial Protection Bureau’s resources for older adults and caregivers.
Educational information only. This article does not provide individualized medical, legal, or financial advice.
0 Comments